Partnerships and equity acquisitions among Korean institutions are accelerating simultaneously in the crypto market. Yet the landscape remains difficult to read at a glance. Announced partnerships are abundant, but actual commercial deployments remain rare. This report examines why the conversion rate is low, and why institutions continue to move forward regardless.
Key Takeaways
- Korean institutional crypto activity has moved beyond MOUs into concrete business operations and exchange equity acquisitions.
- Competition is intensifying beneath the surface as institutions race to claim critical financial infrastructure, including STO standard-setting, stablecoin payment rails, and custody markets.
- Domestic infrastructure builders are emerging as a core pillar of institutional business, constructing Korea-native rails aligned with Bank of Korea CBDC frameworks and local regulatory requirements, reducing dependence on foreign technology.
- The playbook for overseas Web3 foundations entering Korea has shifted entirely, moving from retail community building to partnerships with large corporates and financial institutions, as traditional finance accelerates its takeover of the market.
1. The MOU Arms Race
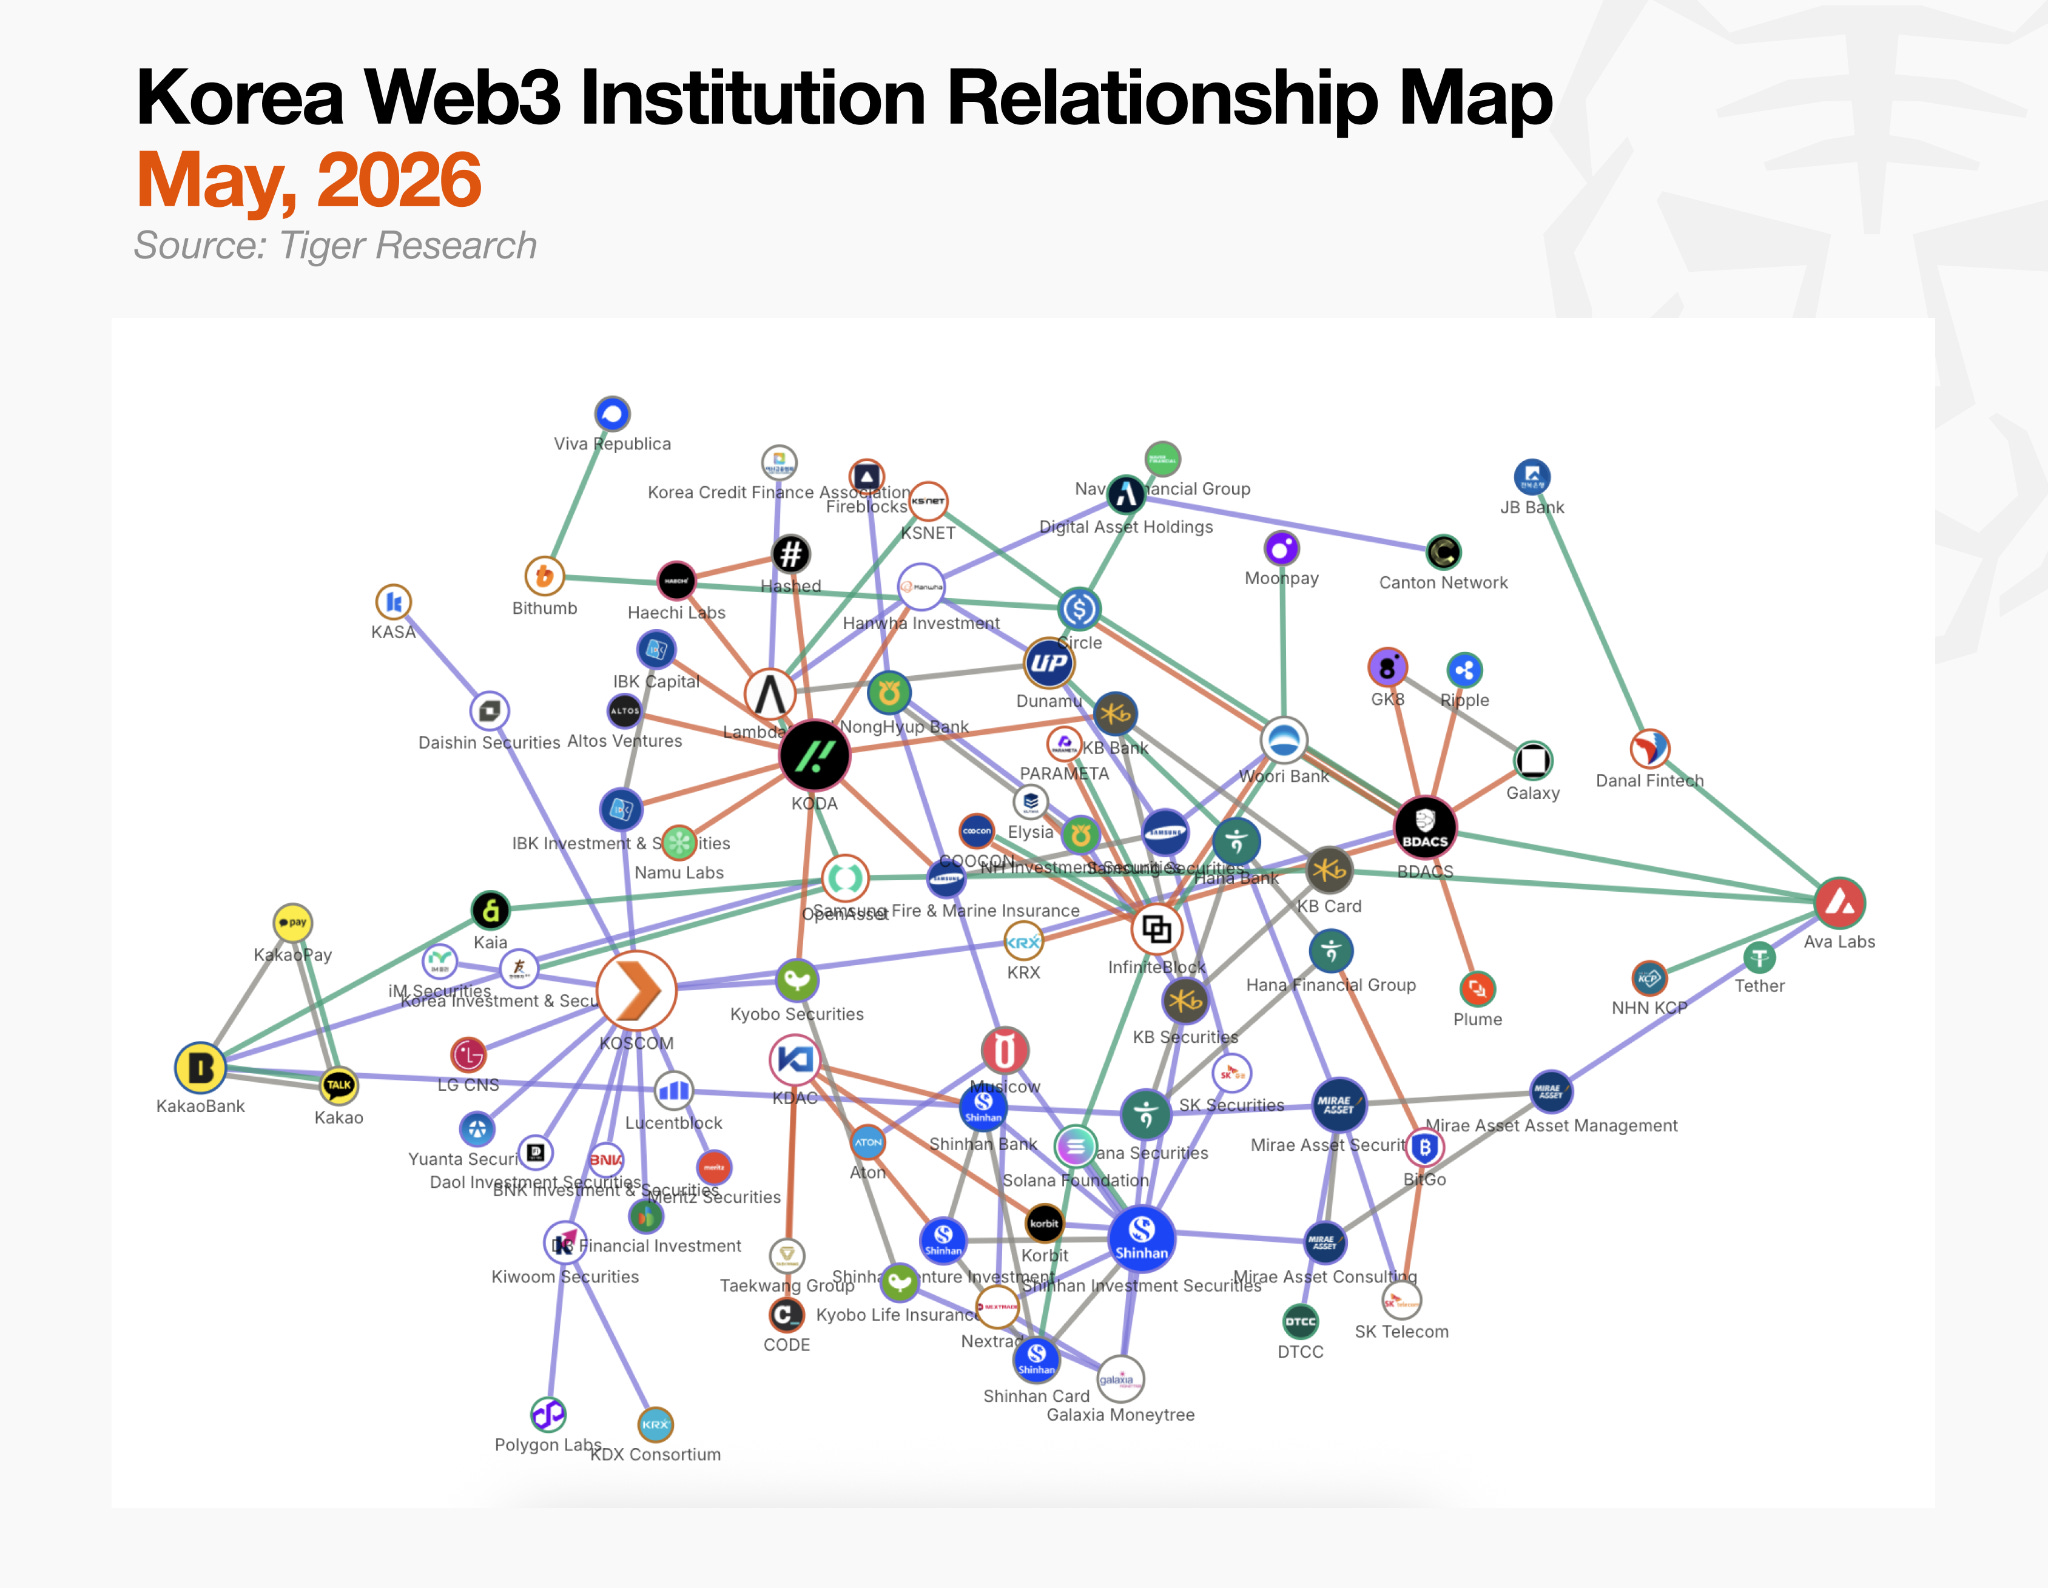
The relationship map above, compiled by Tiger Research, maps the connections across Korea’s institutional crypto landscape. Yet the structure is not easy to read at a glance. It is difficult to distinguish which lines represent active business operations and which are simply MOUs, and the boundary between central hubs and peripheral players remains blurred.
What is notable is that this complexity itself accurately reflects the current state of Korea’s institutional crypto market. As Tiger Research’s dataset of 150 institutions and 196 partnerships confirms, no single hub has yet achieved dominant control over the market.
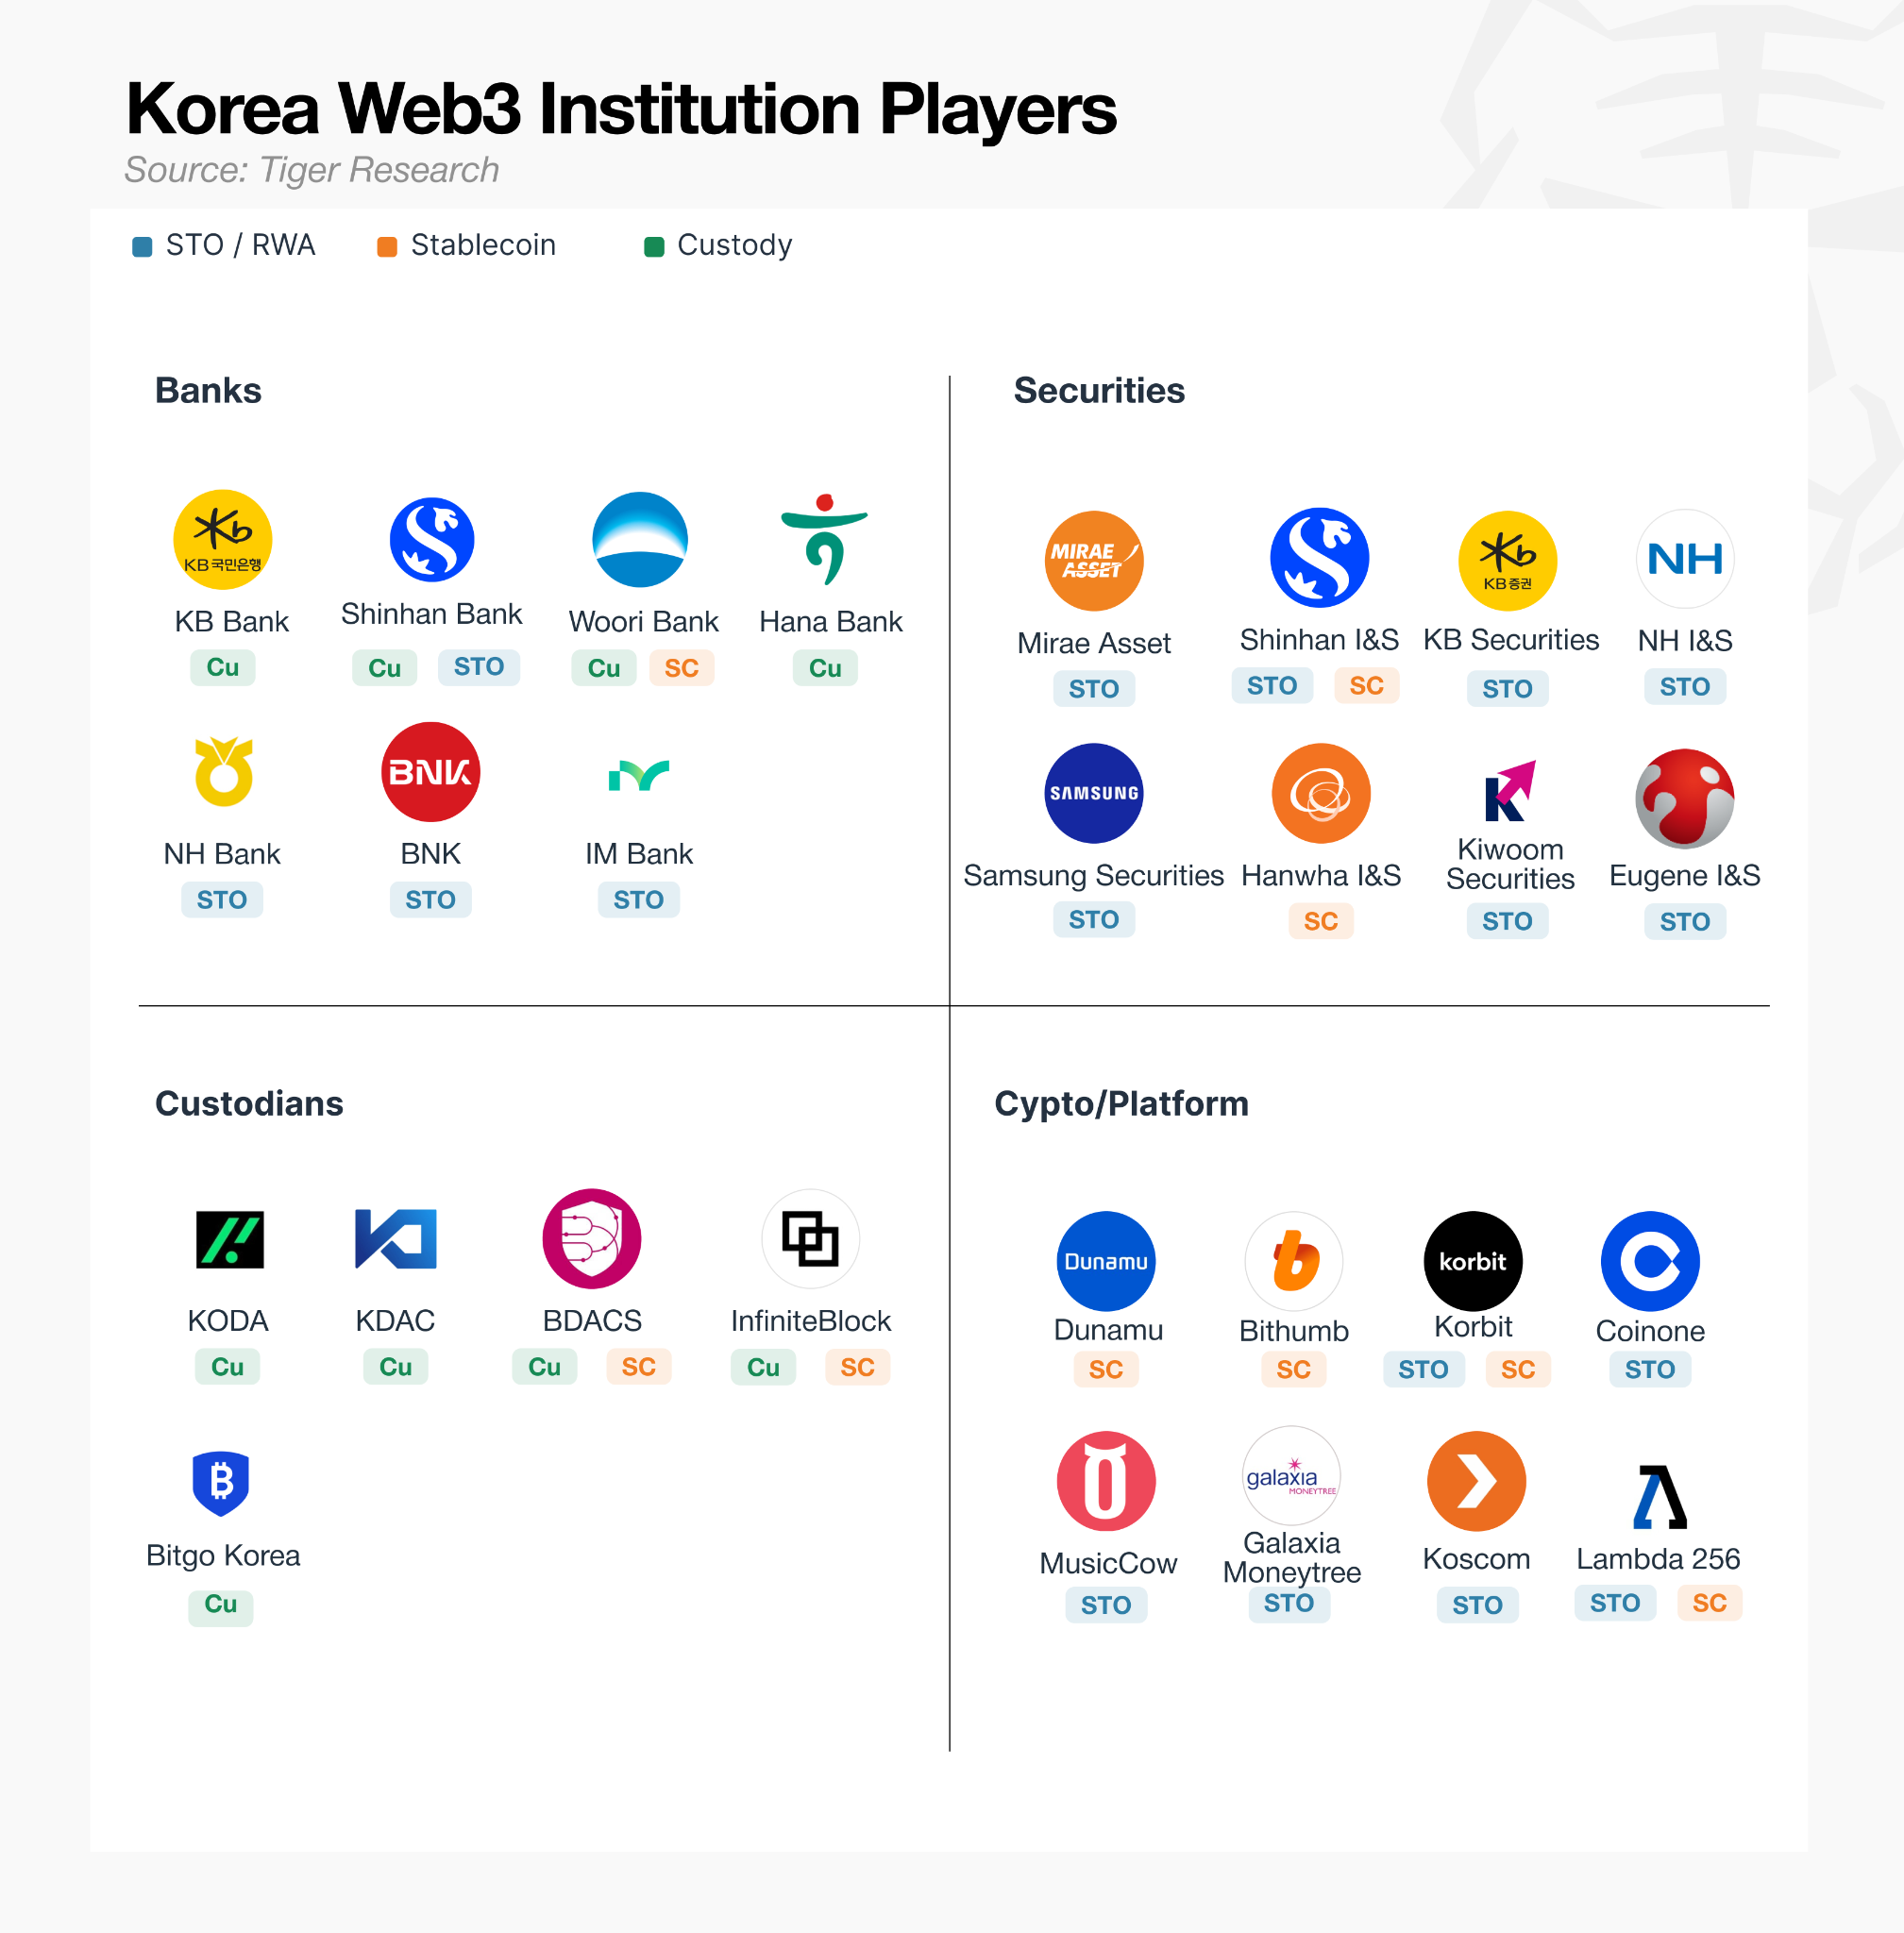
Domestic institutions are simultaneously building their positions across the market before regulations are fully finalized. Competition is currently organized around three fronts: stablecoins, STOs (security token offerings), and custody (crypto asset storage).
Also notable is a sustained wave of financial institutions acquiring equity stakes in exchanges, a move interpreted as a confidence-driven push to secure footholds ahead of full regulatory clarity.
3. Korea’s Crypto Market by Sector
A sector-by-sector look at the relationship map reveals an uneven landscape. Custody has the most operational activity, with a number of players already running live services after clearing regulatory hurdles. RWA and STO, by contrast, remain largely stuck at the contract or MOU stage, waiting for enabling legislation to take effect. Stablecoins face a similar stall, with no clear standard-setter yet in a position to claim market leadership.
Because the nature of the barrier differs by sector, so does the strategy for breaking through. Some players are consolidating domestic coalitions while waiting for regulation to open. Others are turning to overseas markets where regulation has moved faster, carving out alternative paths. The sections below examine the specific barriers and player strategies in each sector.
3.1. RWA/STO: Legislation Passed, Commercialization Infrastructure Is the Bottleneck
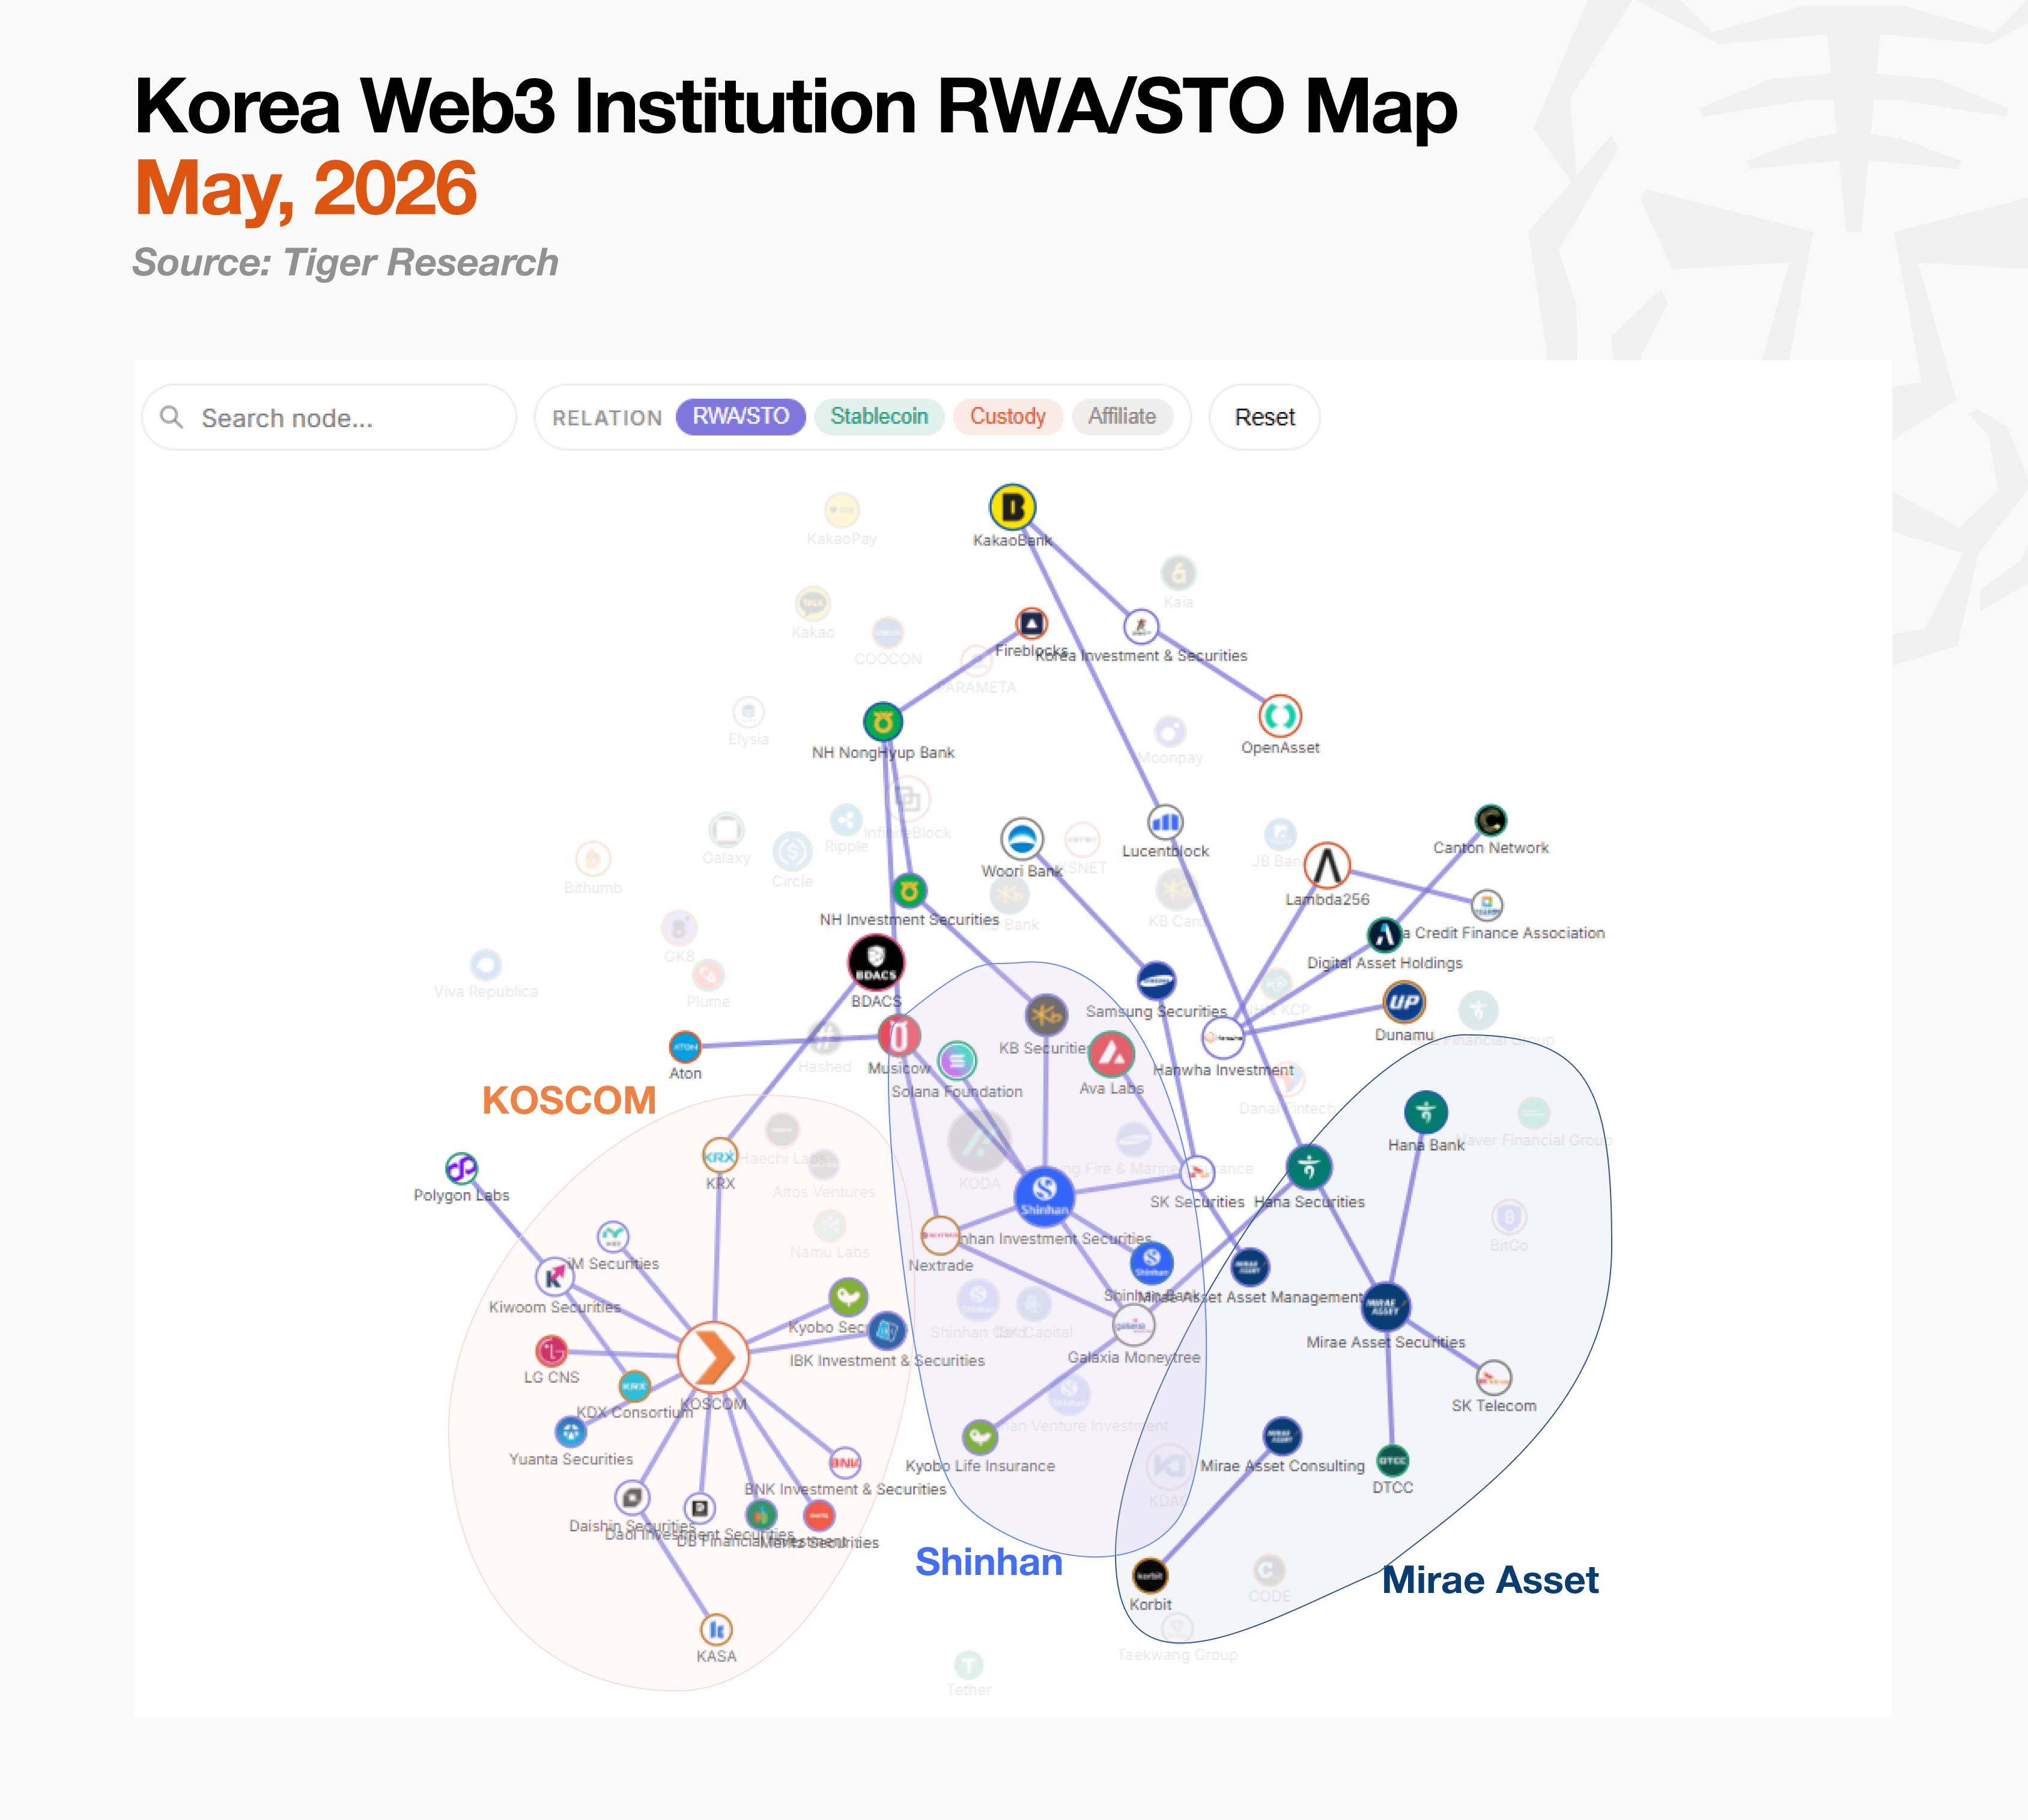
The domestic STO market is divided into two camps: the KOSCOM-led consortium and the Shinhan Investment Securities-led fractional investment alliance. Mirae Asset Securities has taken a separate path, leveraging overseas operations rather than waiting on domestic infrastructure.
KOSCOM, a core financial network operator in which Korea Exchange holds a 76.6% stake, is pursuing a neutral infrastructure model consistent with its founding mandate to provide shared infrastructure for securities firms. Rather than signing exclusive agreements with individual issuers, it is integrating 11 securities firms onto its platform, aiming to set issuance and distribution technology standards and secure interfaces compatible with Korea Securities Depository aggregate custody management requirements.
Shinhan Investment Securities has moved quickly to build its own STO ecosystem. Starting with a proof-of-concept with Lambda 256 in 2022, it launched the joint platform PULSE in 2024 and formalized a multi-platform account integration service in 2025. In 2025 alone, it participated as account manager in 10 investment contract security issuances, and secured a controlling stake in OTC exchange NXT, establishing an end-to-end pipeline from issuance to distribution within its own ecosystem.
Mirae Asset Securities bypassed domestic infrastructure development entirely and moved overseas. It issued a digital bond in Hong Kong, obtained a digital asset retail license from the Hong Kong Securities and Futures Commission (SFC), and plans to launch an MTS in June targeting retail investors in the market. In the United States, it is the only Korean securities firm to join the DTCC-led tokenization working group, which includes JP Morgan, Goldman Sachs, and BlackRock, participating in global standard-setting discussions. The strategy positions Mirae Asset to hold advantages in regulatory alignment and negotiating leverage when domestic STO infrastructure eventually connects to global standards.
3.2. Stablecoins: Legislation, Not Technology, Is the Bottleneck
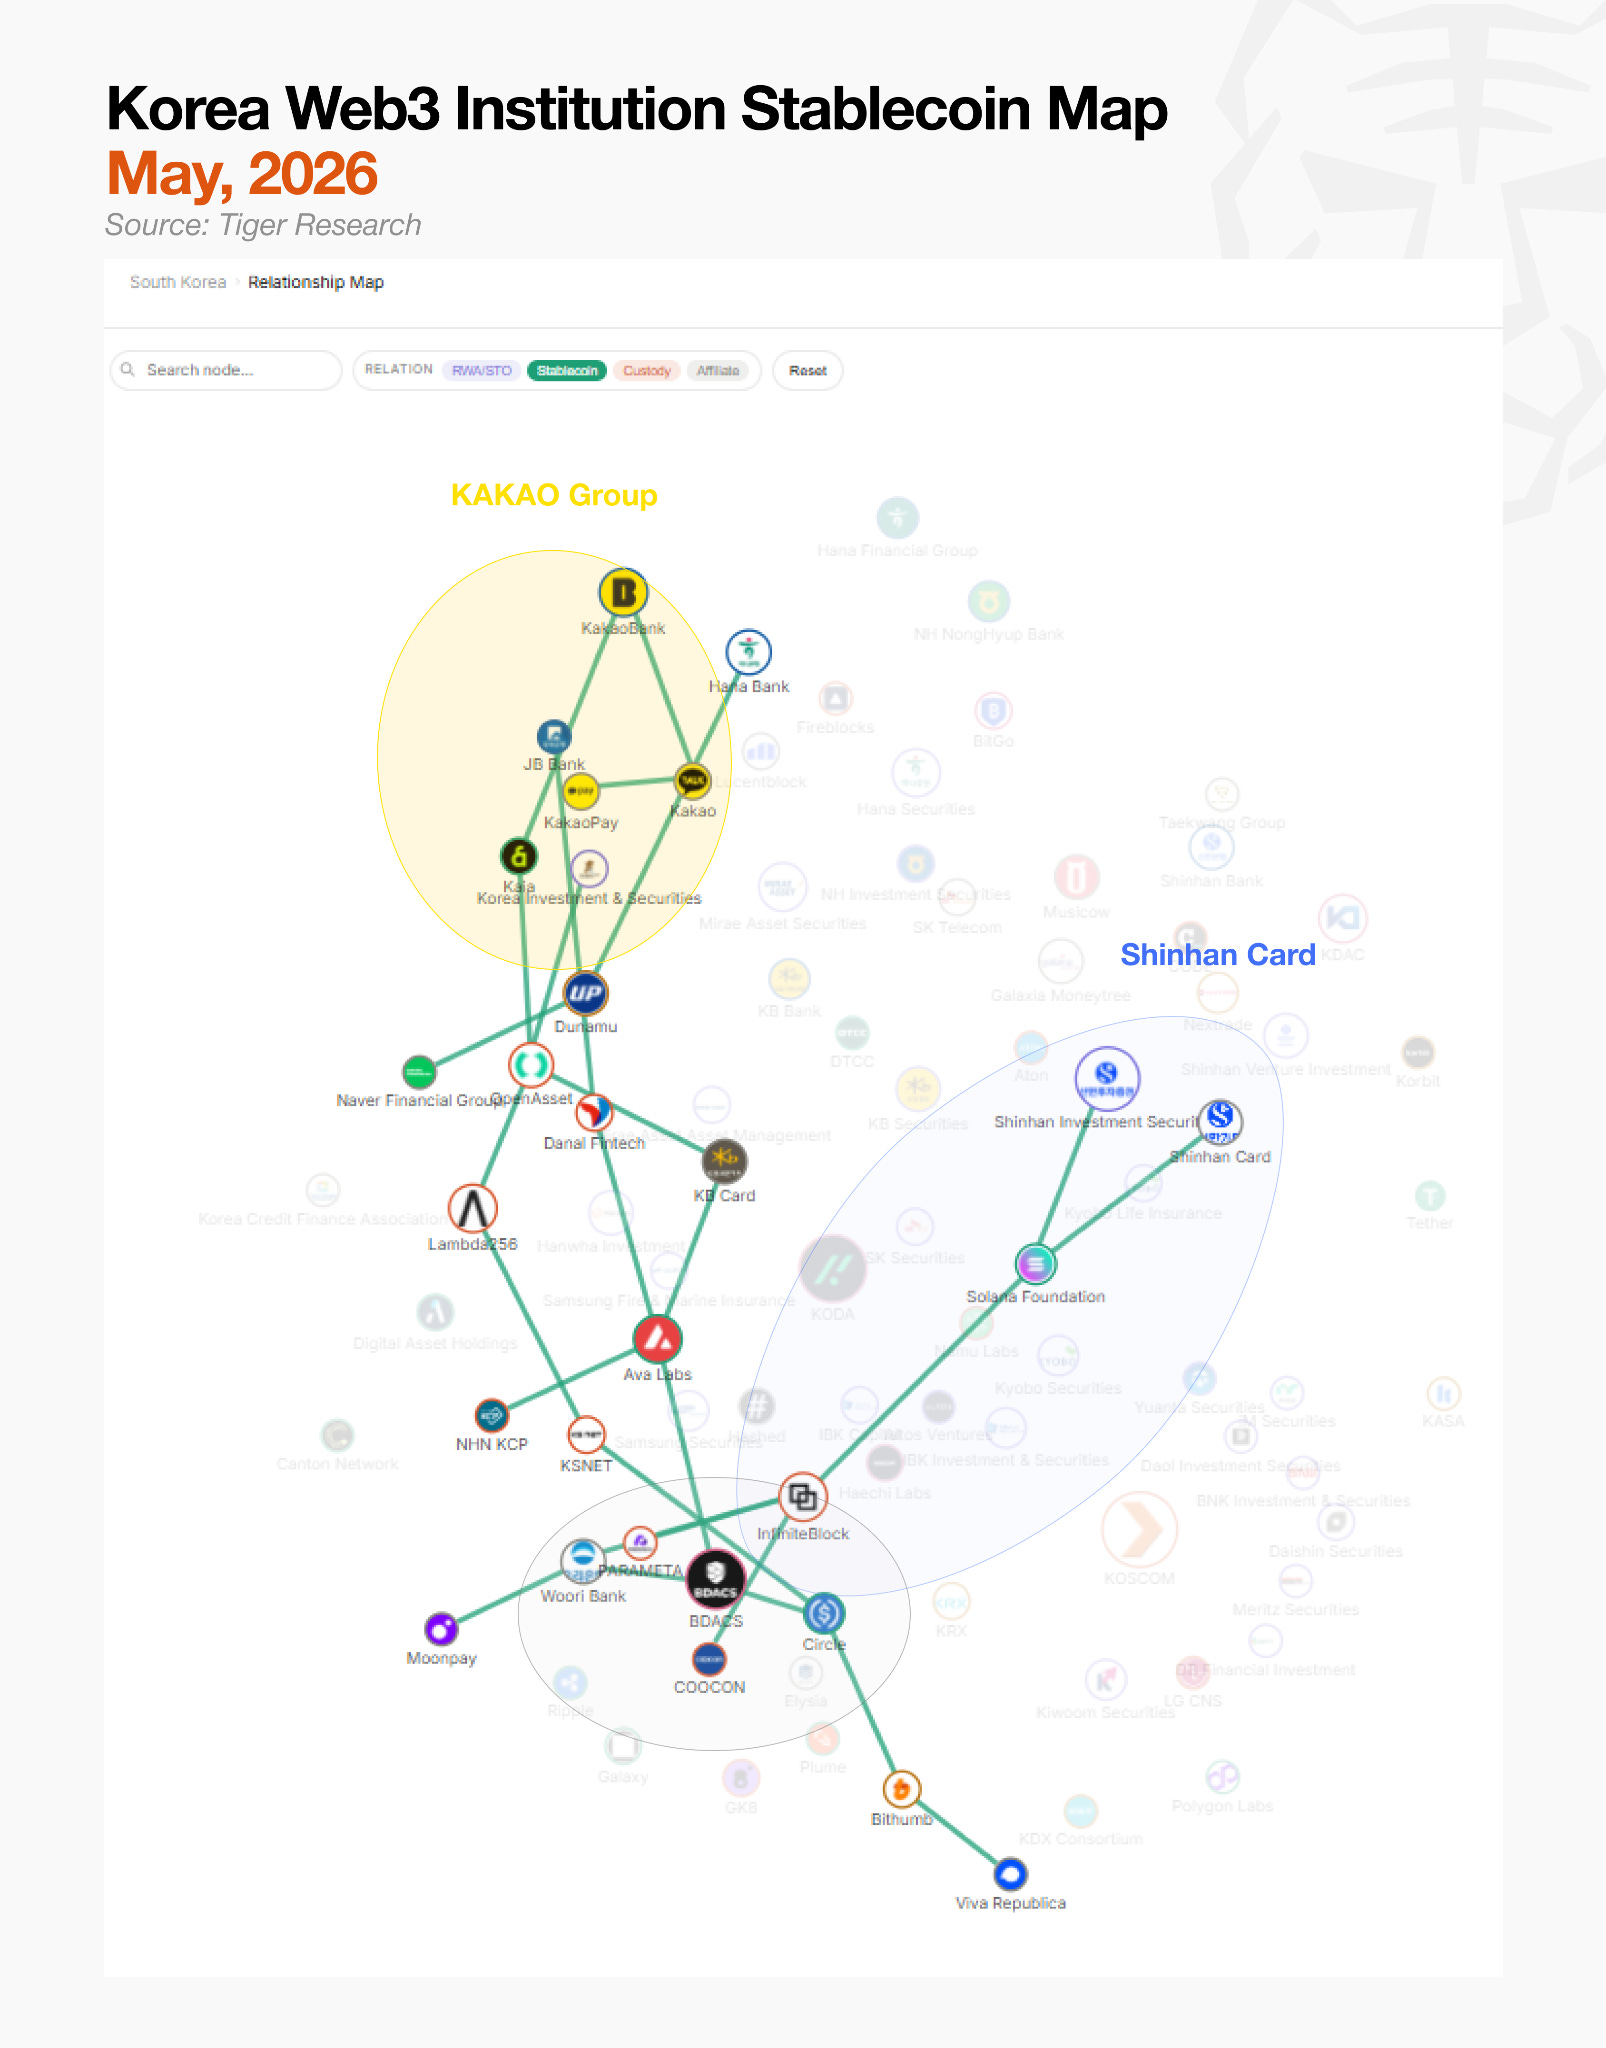
The stablecoin market features a more diverse set of participants than other sectors. Card companies, exchanges, fintechs, and infrastructure firms are each entering through different routes, drawing on their respective strengths.
The largest camp is the Kakao Group. Kakao, KakaoBank, and Kakao Pay have formed a joint task force to build a “super wallet” spanning stablecoins, crypto, and local currencies. Their key asset is the infrastructure accumulated through operating the Kaia public chain since the Ground X era. Kaia has already deployed Tether (USDT) on its network and is conducting live payment tests.
Shinhan Card is focused on migrating its existing payment network onto blockchain rails. Shinhan Card signed an MOU with Solana in April, though the technical groundwork preceded the agreement. The company had already completed an initial proof-of-concept in collaboration with Solana, Visa, Mastercard, and Fireblocks, and is now running advanced tests across six areas including wallets and smart contracts.
The exchange camp is routing around KRW stablecoin delays via dollar stablecoins. Dunamu is developing a KRW stablecoin business with Naver Financial, built on its proprietary blockchain GIWA. Bithumb, facing delays in KRW stablecoin regulation, has chosen to secure a dollar stablecoin distribution network first through partnerships with Circle and WLF. A joint KRW stablecoin initiative with Toss is also under discussion, though progress remains slow.
All camps are active, but all face the same regulatory wall. The Bank of Korea is pushing a 51% rule requiring that only bank-majority consortiums be permitted to issue stablecoins, while fintech firms are pushing back for access, delaying government-ruling party consultations. Once issuance guidelines are released, the camp that has secured the most comprehensive public-facing touchpoints is expected to take market leadership.
3.3. Custody: More Institutional Capital Needed
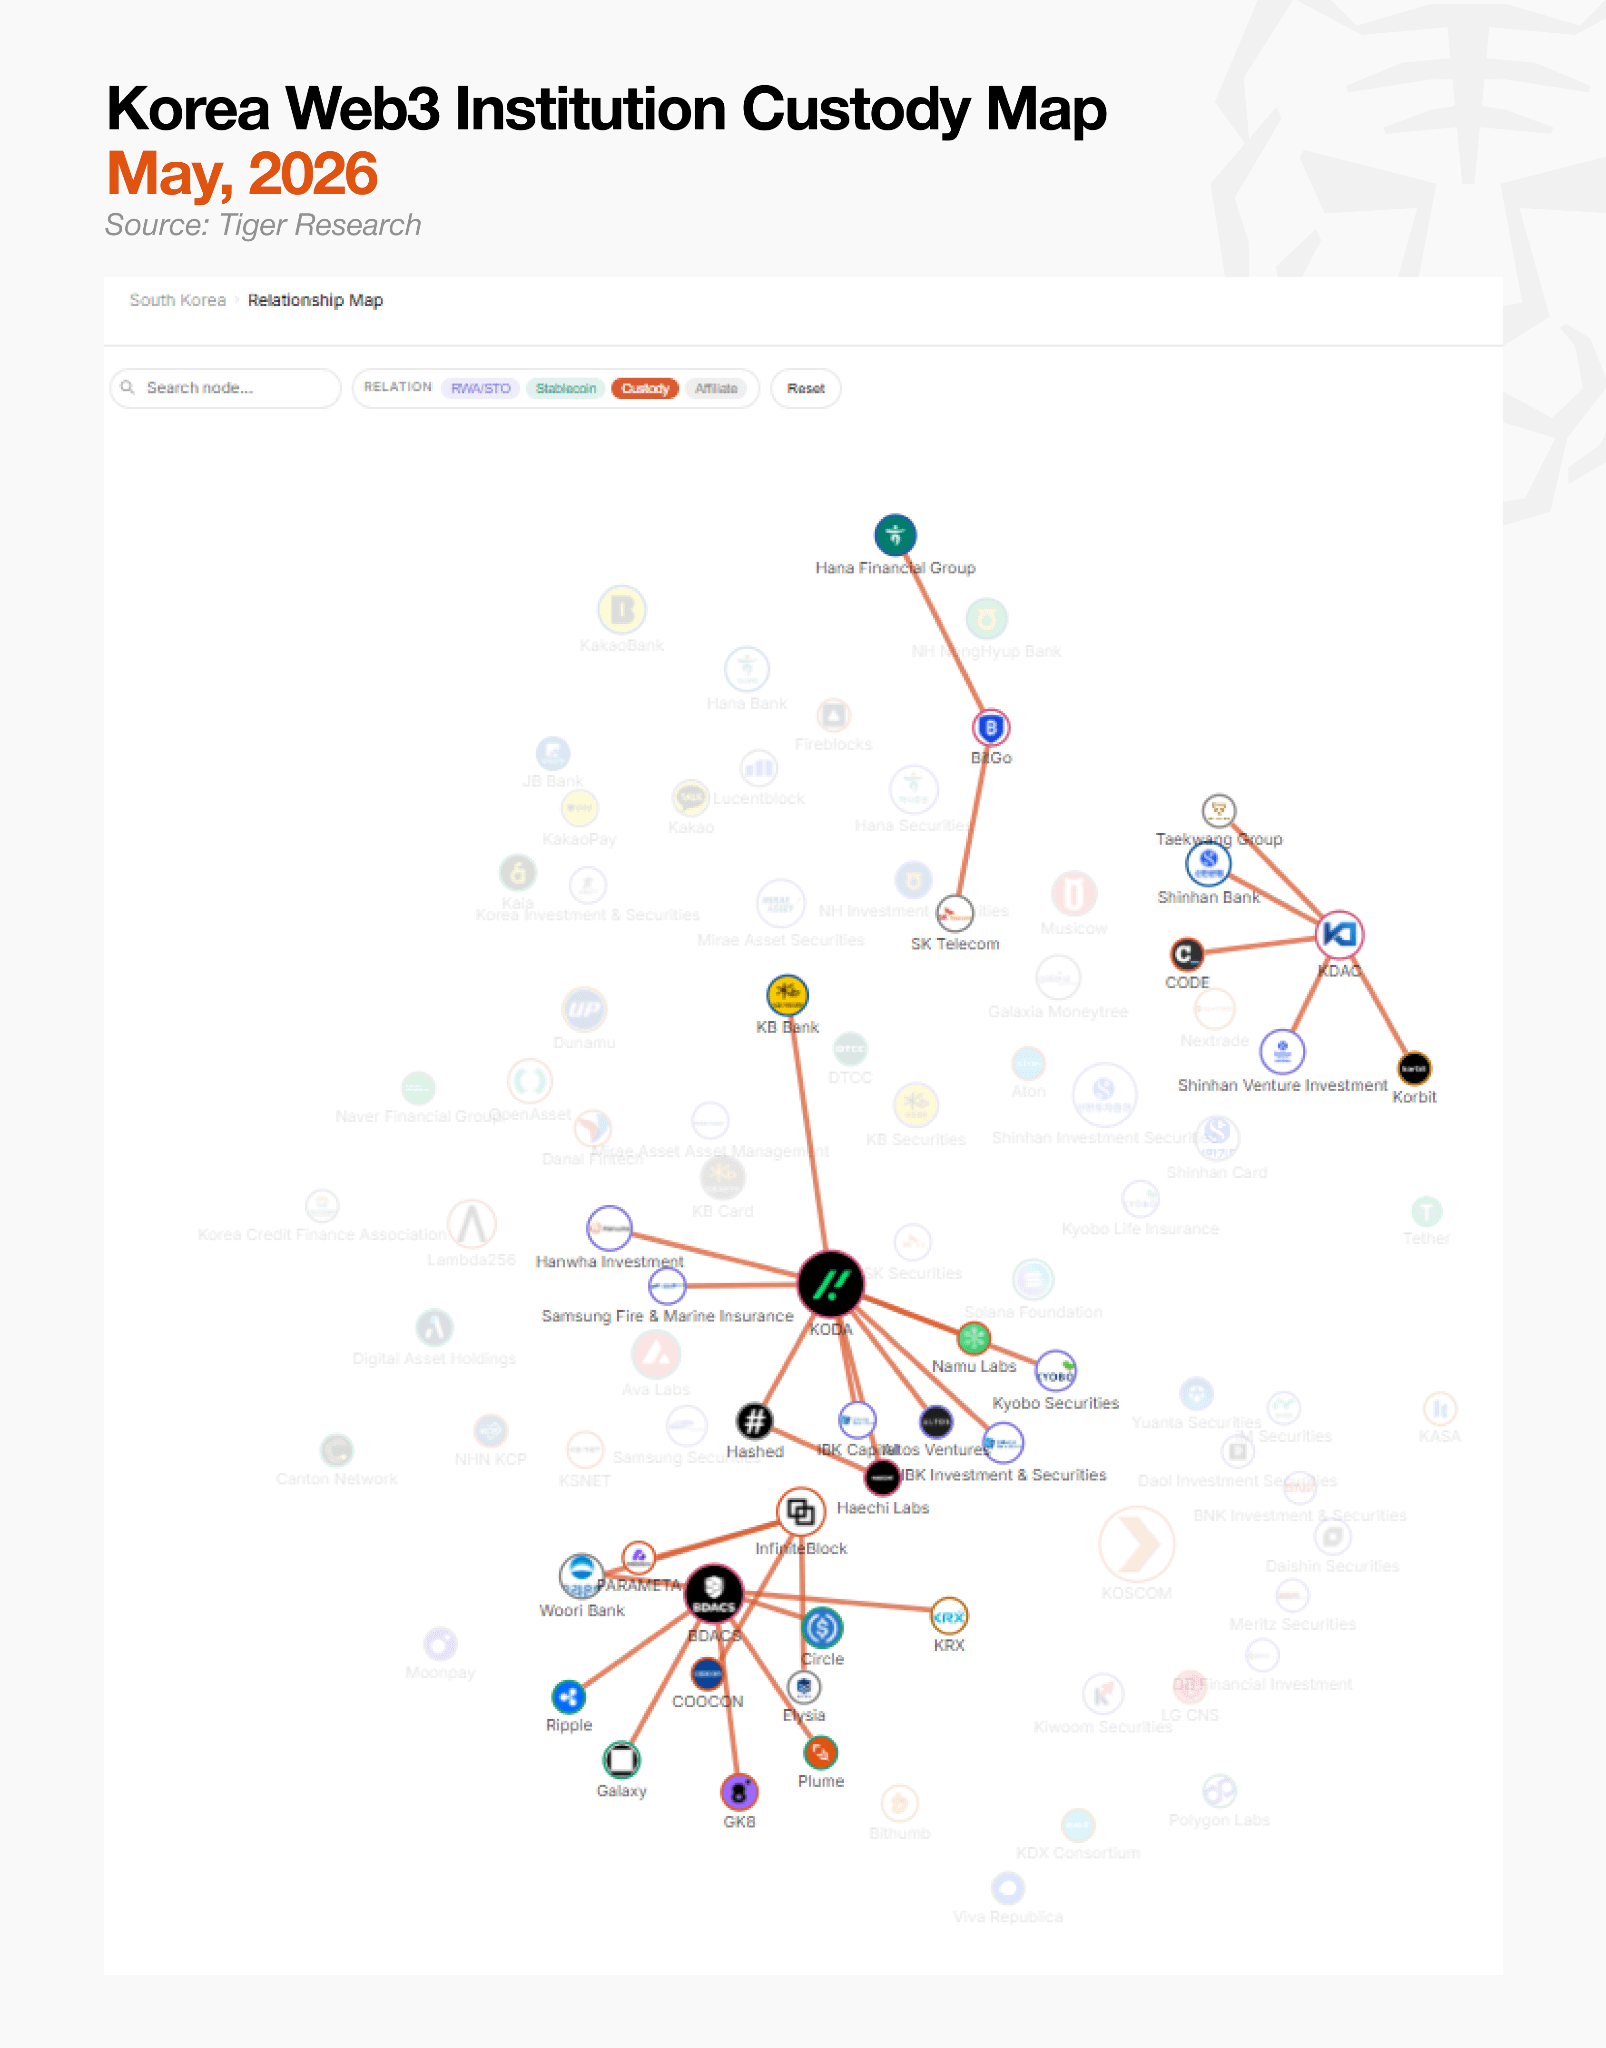
The custody market is structurally simpler than other sectors. Four major custodians have each secured domestic and international financial and technology partners to establish their market positions.
KODA was co-founded by KB Kookmin Bank, Hashed, and Haechi Labs, combining traditional financial capital with crypto-native VC. Hanwha Investment Securities, IBK Capital, and Kyobo Securities have since joined as investors, and a dedicated custody insurance agreement with Samsung Fire & Marine further reinforces its stability.
KDAC is a traditional finance-led custodian with Shinhan Bank and NH NongHyup Bank as major shareholders. NH NongHyup Bank was originally an investor in a separate custodian, Kardo, and became a KDAC shareholder following a merger. Post-merger, KDAC counts two of Korea’s five major banks among its shareholders.
BDACS has taken a distinct approach centered on technology and partnership development. Expanding custody and payment infrastructure through a partnership with Woori Bank and international digital asset infrastructure firms including Galaxy and GK8, it has also signed an MOU with Circle to issue the KRW stablecoin KRW1 on Circle’s Arc blockchain, and is the sole VASP and a key custody partner in the KRX-led KDX consortium. Currently conducting a PoC for KRW1, BDACS is positioning itself as a custodian targeting both custody and payment infrastructure simultaneously.
BitGo Korea entered the domestic market on the strength of its global parent’s technology. BitGo’s headquarters custodies over USD 70 billion in assets and processes approximately 20% of all Bitcoin on-chain transactions globally. Domestically, Hana Financial Group and SK Telecom each hold stakes, making it a custodian backed by both financial and telecommunications capital.
Various institutions have entered the market through their respective custodian relationships. However, all major custodians are reported to have posted net losses last year, suggesting they have built ahead of the institutional capital flows needed to sustain operations.
Taken together, the infrastructure buildout across STO, stablecoins, and custody reveals a clear common limitation: domestic institutions have constructed their business frameworks, but the underlying technology infrastructure remains largely dependent on overseas solutions.
5. Retail Out, Institutions In
The recent surge in partnership announcements should not be read as ordinary business development. These are positioning moves: institutions are staking out favorable arrangements before regulation is finalized, then using those arrangements to shape what the regulatory framework ultimately looks like. The current partnership race is less about market capture and more about regulatory design.
Korea’s crypto market has restructured significantly in just six months. Custody camps have formed, STO consortiums have taken shape, and major financial holding companies have moved to acquire exchange equity. Meanwhile, retail trading volume has declined sharply. Combined trading volume across Korea’s five major exchanges fell approximately 48% year-on-year. The market’s center of gravity is shifting rapidly from retail to institutional.
This shift has also changed how overseas crypto foundations approach Korea. Just as Solana was adopted as Shinhan Card’s partner and Avalanche as Mirae Asset’s, foundations entering the domestic market have shifted their primary focus from exchange trading volume to partnerships with financial institutions and large corporates. The community meetup model that once drove retail liquidity is no longer effective.
The results of this market restructuring are expected to become visible at KBW 2026, taking place in Seoul this September, an event that consistently reflects prevailing market conditions. A look at the confirmed speaker lineup already shows traditional finance figures in the majority. Where last year’s overseas foundations competed through token-incentivized community side events, this year’s focus is expected to shift toward substantive business discussions.
